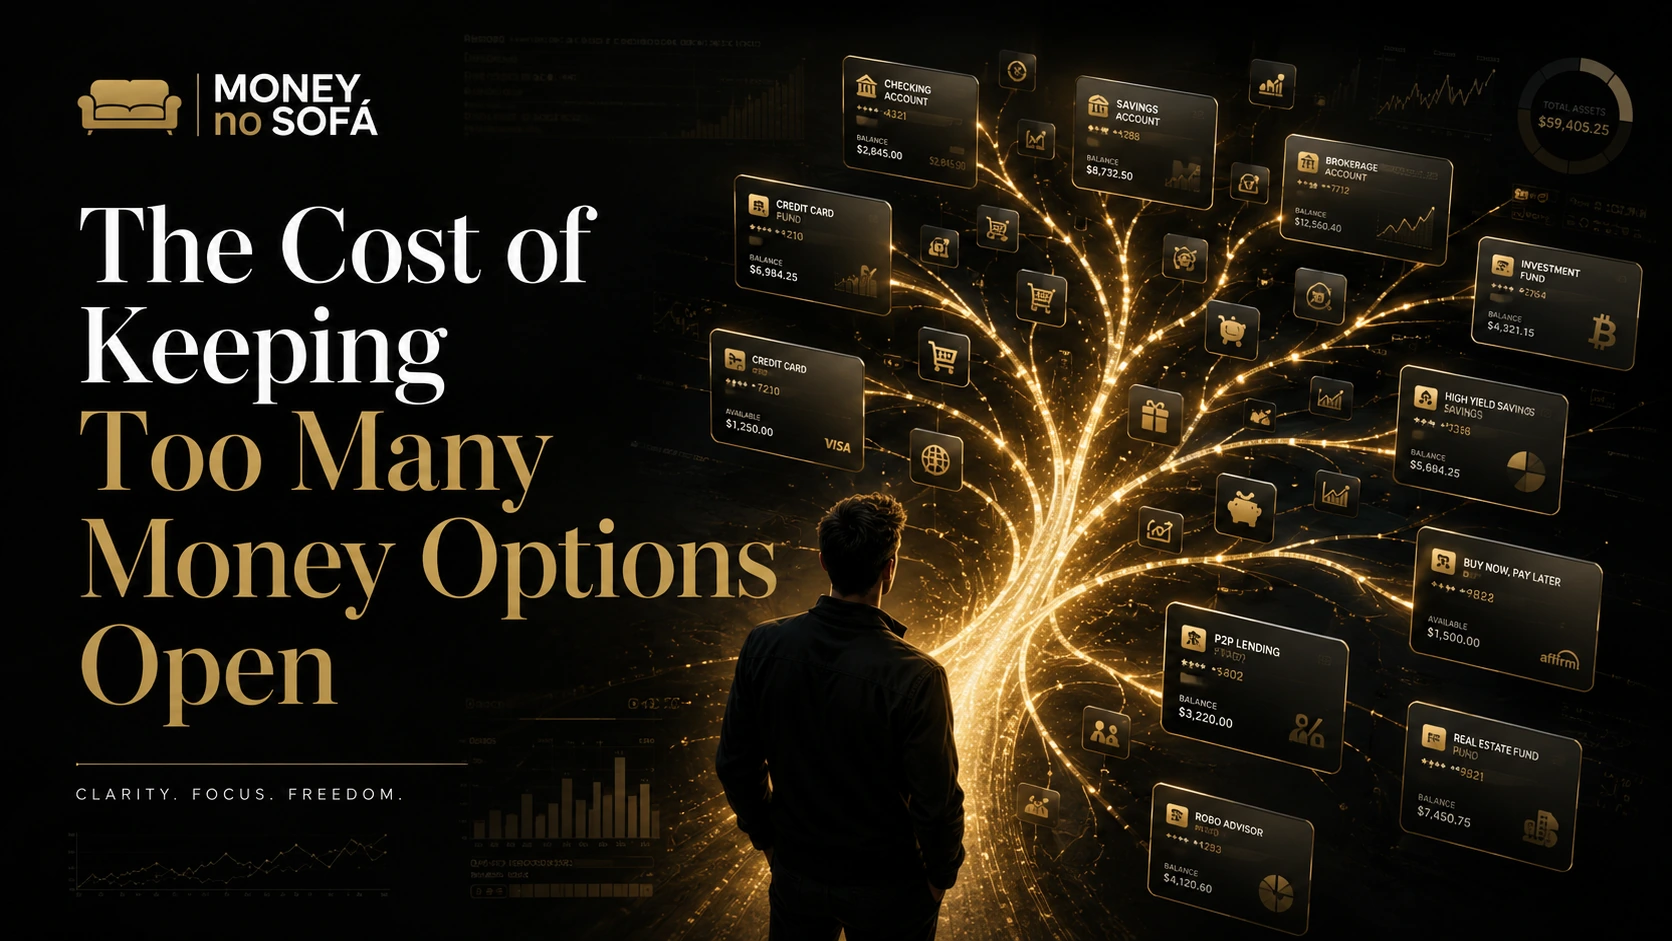
Too many financial choices can create stress, delay and weak decisions. Simplifying your options can make money easier to manage.
Keeping options open sounds smart. In money decisions, it can become expensive.
Too many accounts, too many cards, too many savings goals, too many investment choices and too many “maybe later” purchases can create a system where nothing feels final and everything demands attention.
More choices can reduce action
When every dollar could go to ten different goals, deciding what to do with it becomes harder. That often leads to delay.
You might keep cash sitting in the wrong place because you have not chosen an account. You may keep an expensive service because you are still “comparing alternatives.” You may postpone saving because you have not decided which goal comes first.
The option to decide later becomes the default decision.
Financial clutter creates hidden work
Every extra account or product has maintenance:
- passwords and statements;
- fees and renewal dates;
- tax documents;
- minimum balances;
- security monitoring;
- mental tracking.
The cost is not only money. It is attention.
A system can look diversified while actually being fragmented.
Priorities need an order
One of the simplest ways to reduce financial noise is to create a sequence instead of trying to optimize everything at once.
For example:
- cover essential bills;
- maintain an emergency buffer;
- pay high-cost debt;
- fund one or two current goals;
- invest for longer-term priorities.
Your exact order may be different. The value comes from having an order at all.
Optionality is most valuable when circumstances are uncertain
There are times when keeping options open is rational. If your income is unstable, a move is coming or a major decision is unresolved, holding extra liquidity can be more useful than forcing money into a long-term commitment.
But uncertainty should be named. Otherwise “I want flexibility” can become an excuse for indefinite indecision.
Simplify before you optimize
People often search for a better rate, better card or better investment while their basic financial architecture remains messy.
Optimization gives small gains when the system underneath it is unclear.
Before adding another product, ask whether something can be consolidated, closed or automated.
Good money systems are easier to explain
If you cannot describe your system in a few sentences, it may be doing too much.
A simple explanation might be: “Bills come from this account. Emergency savings stay here. Long-term investing happens automatically. This card is for daily spending. Everything else has a specific reason.”
That clarity makes behavior easier because each part of the system has a job.
List every financial account, card and active money goal you manage. Circle anything that has no clear purpose. Your next financial improvement may be removing something, not adding something.
Money no Sofá — Money for real life.
The headline is only the start.
Ask Nova what this story could change in your budget, savings, debt, investments or next purchase.
