IMF sees 3.1% growth, with a widening gap.
GLOBAL · IMF · AI · OCTOBER 13, 2026
The world economy is still growing. The question is who is paying to keep it moving—and how long that arrangement can last.
The International Monetary Fund’s October 13 World Economic Outlook puts global growth at 3.1% in 2026 and 3.4% in 2027. That first number is a modest improvement on the Fund’s July estimate of 3.0%. It is not, however, an all-clear signal for household budgets, businesses or investors. The IMF’s more important message is that the sources of growth are becoming unusually uneven: spending on artificial intelligence supports some countries and suppliers while high energy prices and financing costs weigh on others.
What the headline number hides
A global growth forecast is an average of economies facing very different conditions. The country expanding because its factories supply AI hardware is not living through the same cycle as the importer trying to absorb expensive fuel. The Fund expects consumer inflation worldwide to average 4.7% in 2026. These are forecasts, not measured final outcomes, and national prices will differ substantially.
That distinction matters because a stronger global GDP forecast does not guarantee a stronger paycheck. It is possible for output to rise while some households continue to face costly groceries, transport and credit. It is also possible for technology investment to support a nation’s production without generating equally distributed income gains. The practical question is less ‘Is the world growing?’ and more ‘Which part of that growth reaches my employer, my clients and my bills?’
AI spending has become a macroeconomic force
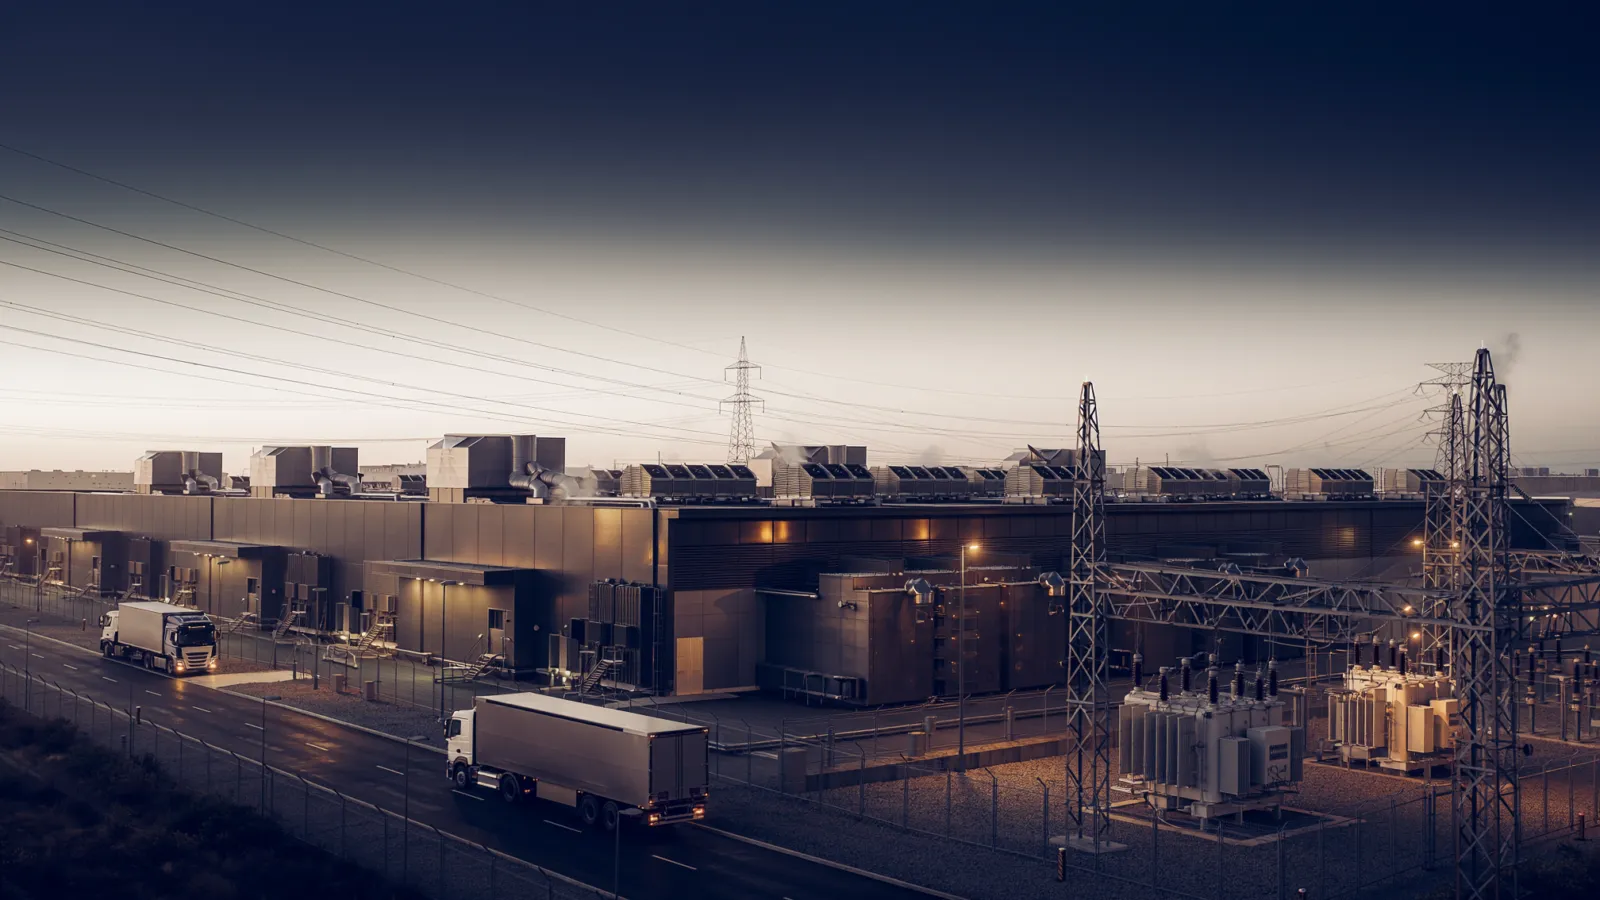
Data centers need computing equipment, electricity, construction, cooling, networks and financing. When investment accelerates, orders ripple through semiconductor suppliers, industrial facilities and logistics networks. This is why the AI cycle is no longer only a technology-stock story. It can affect capital expenditure, trade flows and local labor demand.
But a spending boom and a profitable business model are not the same thing. Builders can expand infrastructure before customers generate enough revenue to justify the expense. Companies funding projects with debt face a second question: what happens if future income arrives later than planned? A slowdown could hit equipment orders and financing conditions even if AI tools continue to improve. The IMF describes the risks as two-sided: stronger productivity would help, but overly optimistic expectations could trigger market corrections.
Energy is the other side of the equation
The Fund’s outlook comes against disruption in the Middle East and elevated energy prices. Expensive oil does not stop at the fuel pump. It can enter the cost of freight, food distribution, industrial heat, airline travel and electricity in markets where generation or pricing depends on fuel. How much of that pressure reaches customers depends on contracts, taxes, competition, inventories and exchange rates.
Businesses face a difficult timing problem. An importer may pay more for transport before it can adjust prices. A small manufacturer may see a higher energy bill while customers resist a price increase. A family may experience a tighter budget even without any change in its wage. None of these outcomes follows mechanically from one global oil quote, but they explain why the Fund warns that the economy has less room to absorb repeated shocks.
Why borrowing costs matter even when rates do not change today
Government debt and bond yields form another link between global forecasts and ordinary decisions. If lenders demand more compensation for inflation or fiscal risk, long-term borrowing costs can remain high even when a central bank is considering cuts to short-term rates. Banks and companies then reassess mortgages, business loans and investment projects.
This does not mean the IMF report itself raises anybody’s interest rate. It means that the underlying risks—energy inflation, large financing needs and debt sustainability—can influence the conditions under which lenders set prices. A household shopping for a mortgage should compare actual offers and total costs rather than assume a favorable world GDP forecast means cheaper financing is imminent.
Three questions for a business owner
First, is revenue exposed to the AI investment cycle, directly or through customers? A supplier serving data centers may benefit from the build-out, while a company dependent on discretionary spending may not. Second, which costs could move before selling prices do—energy, freight, inventory or interest? Third, how much cash is available if a major customer delays an order or a lender changes terms?
These questions are more useful than betting on a single headline. A resilient company can model higher input costs, slower collections and an interruption in financing. It can also distinguish a real productivity gain from a software subscription that adds expense without changing output.
What households can actually control
A family cannot determine the next global growth print. It can check the interest rate on existing debt, compare fixed and variable expenses, keep emergency savings appropriate to its circumstances and avoid treating a forecast as an investment instruction. If a new device or AI service promises higher income, the important test is whether the expected savings or revenue can be measured after fees and time are included.
For investors, the report is not a buy-or-sell signal. It identifies exposures that deserve scrutiny: concentration in AI-related expectations, sensitivity to bond yields and the possibility of another energy shock. Portfolio decisions still depend on risk tolerance, time horizon and diversification.
The next signal to watch
Watch three developments together: whether companies begin reporting measurable returns on AI spending, whether energy and shipping disruptions ease, and whether government borrowing costs stabilize. One indicator alone may be misleading. A strong chip order book can coexist with weak consumer demand; a calmer oil market can coexist with tight credit.
The IMF’s 3.1% forecast says the world economy is still advancing. It does not say the benefits are evenly shared, or that the costs have disappeared. The Money no Sofá lens is simple: identify the channel from global growth to your income, costs and decisions before acting.
Useful next step: Ask NOVA to map how higher energy prices, credit costs or AI spending could affect your own budget or business.
Sources and methodology
Primary: IMF, World Economic Outlook press release, October 13, 2026; IMF World Economic Outlook database, October 2026. The figures are IMF projections, not final outcomes. MNS interpretation is independent and does not constitute individualized financial advice.
The headline is only the start.
Ask Nova what this story could change in your budget, savings, debt, investments or next purchase.
